Financial systems modeling
Build a visual model of the capital, incentives, constraints and uncertainty behind a financial decision, then inspect its rules and compare scenarios with the people who know the domain.
Trusted by Professionals within the Finance Industry from around the World


Design, forecast, and optimize resilient financial systems with precision. Harness the power of intelligent financial modeling for a forward-thinking approach in the dynamic landscape of finance.
Design
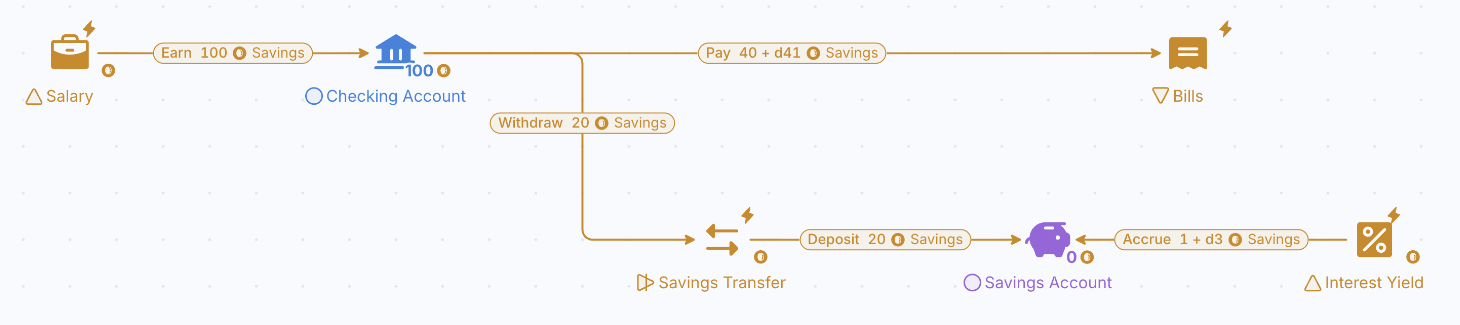
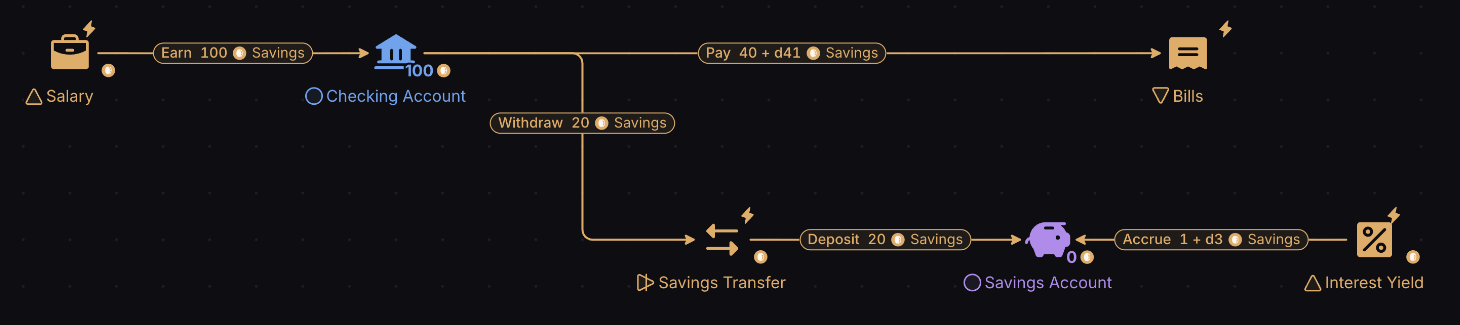
Create playable diagrams for any system, regardless of complexity. Make feedback loops and economies easier to validate, communicate and understand.
Predict
Gain data-driven insights by employing out-of-the-box Monte Carlo simulations. Test what-if scenarios and measure their impact in a safe, virtual environment, with one click of the button.
Balance
Move the Levers of a model, Forecast what each change does and compare the Outcomes of every Scenario, so a system is balanced on evidence rather than trial and error.
What you can do with it
Portfolio management
Model portfolios by asset allocation, risk tolerance and market trends.
Risk assessment
Simulate market volatility, interest rate changes and geopolitical events, and see their effect on portfolios.
Financial planning
Estimate long-term plans from income, expenses, inflation and investment returns.
Algorithmic trading
Model the feedback loops of trading systems to see their effect on liquidity and prices.
Cash flow analysis
Predict liquidity needs and find bottlenecks in the cash flows of an organization or portfolio.
Market microstructure
Model order routing, liquidity and high-frequency trading under different market conditions.
Monte Carlo simulation in financial forecasting
Monte Carlo simulations are widely used in finance, particularly for analyzing the projected growth of a stock portfolio over time.
These simulations are invaluable for financial planning, as they enable investors to comprehend the potential risks and rewards over a long-term horizon, facilitating informed decisions regarding investment strategies and retirement planning.
Assuming an individual contributes $6000 annually to their portfolio, with an anticipated mean return of 7%, a standard deviation of 15% and a 1% annual fee, the simulation model calculates the investment’s growth over time, incorporating variability to reflect market fluctuations. The annual contribution is the consistent amount added to the investment each year. The mean return represents the average expected annual percentage increase, while the standard deviation measures the return’s variability.
The model simulates each year’s growth by adjusting for the expected variability, and after a specified period (for example, 50 years), it provides a distribution of potential end values. During each iteration of the simulation, the end value for the year is determined by applying the mean return and standard deviation to the annual contribution, assuming a normal distribution of returns. After 50 years, the simulation yields a range of possible outcomes, estimating the probability of different end values based on the parameters set. Four Levers let you change the assumptions yourself: Yearly contribution ($/year), Expected return (%/year), Market volatility (%) and Annual fee (%). Press Play to watch the Portfolio Vault grow, then run a Forecast to see how wide the range of outcomes is.
Stress-test the portfolio before the market does
Model cash flows, rates and exposures as a system, then Forecast the range of outcomes before you commit capital.
- ISO 27001 certified
- SSO & SAML
- GDPR compliant
- Trustpilot verified
- Red Herring Top 100
- Dealroom Rising Star